Asset Protection for Landlords: How I Structure My Rentals in LLCs After Being Sued Three Times
Sued three times as a landlord — one case cost $250k. Here's how I hold my rentals in LLCs under a Wyoming holding company to protect personal assets.
I've been sued three times as a landlord. The third one was never actually filed — it was drafted and waved at me to intimidate, which tells you something about how these things go. All three were unpleasant. One of them cost me $250,000 in legal fees before it was over. I did not enjoy the education, but I got one.
Here's the first lesson, and it's uncomfortable: if you build any real net worth, you become a magnet for the entitled and for a certain slice of the legal profession — and I use the word profession loosely. A visible, collectible target invites claims that a judgment-proof one never sees. You can't change that you own things. You can change how you own them.
This post is how I hold my properties now, and why. I'm not a lawyer or a CPA, and none of this is legal or tax advice — the whole point is that you should build this with professionals who know your state. But I wish someone had drawn me the map before I learned it the expensive way.
My original mistake: everything in our personal names
For years I held every property in my wife's and my personal names. It felt simpler. It was a mistake.
The moment it became obvious was in the middle of one of those lawsuits. I went to draw on a line of credit to fund my legal defense — and learned that a credit application asks whether you are involved in any pending litigation. Answer honestly, and you get denied. So exactly when you need liquidity most, the fact that you're being sued personally slams the door on borrowing to defend yourself. The lawsuit had reached into a part of my life that had nothing to do with the property, because I was the defendant, not an entity.
When you own property in your own name, there is no wall between "the rental" and "you." A claim about a cracked step at one duplex can put a lien on your home, your brokerage account, and every other property you own. That's the exposure I set out to fix.
The structure I use now
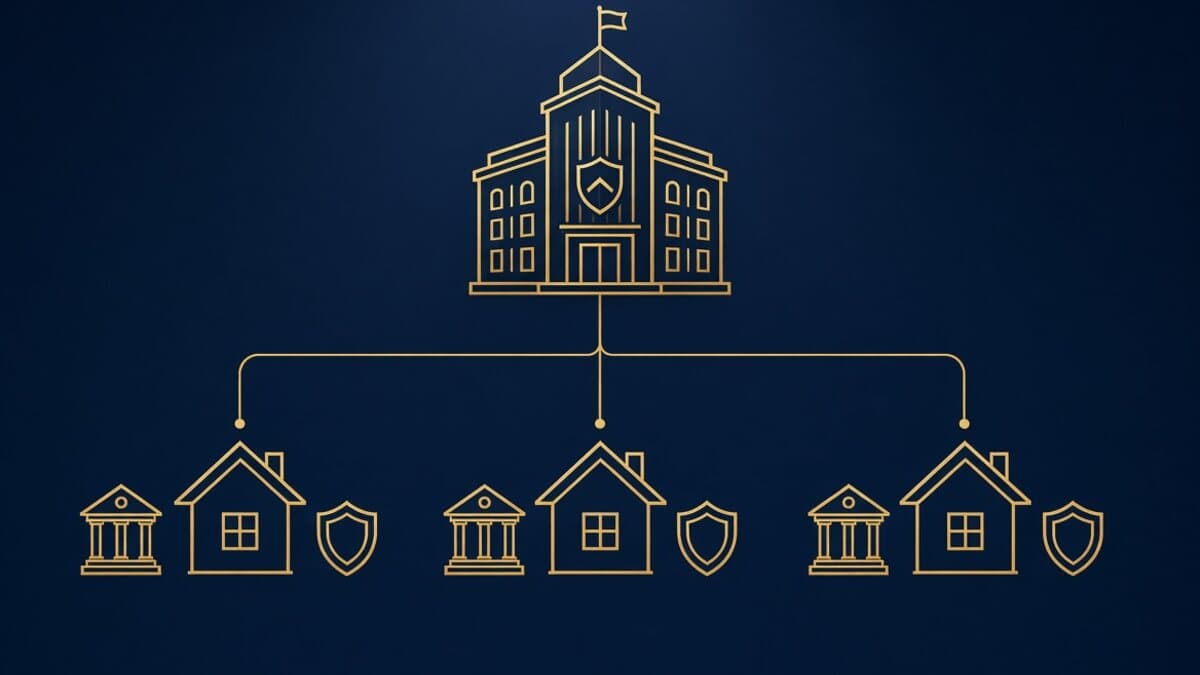
Here's the shape of it, top to bottom:
| Layer | Entity | Registered in | Job |
|---|---|---|---|
| Top | Holding company (LLC) | Wyoming | Owns the property LLCs; receives the profits |
| Middle | One LLC per property | The property's own state | Holds title, operates, contains liability |
| Ground | The property itself | — | Deeded into its property LLC |
Why Wyoming for the holding company
The holding company sits at the top and owns the individual property LLCs. I based it in Wyoming for a few concrete reasons:
- Charging-order protection. In Wyoming, if a creditor wins a judgment against you personally, their remedy against your interest in the LLC is generally limited to a charging order — a right to distributions if and when they're made — rather than seizing the company or forcing a sale. That's a strong deterrent.
- No state income tax and low annual fees, so the holding layer is cheap to maintain.
- Privacy. Wyoming doesn't publish member names in the public record, so the ownership chain isn't sitting in a search result for a plaintiff's attorney to admire.
Because the holding company only owns other companies and doesn't itself operate in any particular state, it can stay Wyoming-based without triggering registration elsewhere.
Why each property LLC registers in the property's state
Each property lives in its own LLC, registered in the state where the property physically sits, and that LLC is owned by the Wyoming holding company.
The reason is simple: an LLC that owns and rents real estate in a state is doing business in that state. To legally hold title there, open a local bank account, and be able to sue or be sued in that state's courts, the entity has to be formed or foreign-registered there. A single Wyoming LLC holding a California property doesn't dodge California — it would still have to foreign-register in California and pay California's fees (that state's $800 minimum franchise tax is the classic example). So the clean, honest setup is a property LLC registered in the property's own state, sitting under the Wyoming holding company. One property, one LLC, in the right jurisdiction.
Banking: a separate account (and EIN) for every property
Every property LLC gets its own EIN and its own business checking account. Rent comes into that property's account. Its mortgage, taxes, insurance, and repairs are paid out of that same account. Personal money never touches it, and it never touches personal money.
This part is not optional, and it's where a lot of landlords quietly undo their own protection. The single fastest way a plaintiff pierces the LLC — "pierces the corporate veil" — is to show you treated the company as your personal wallet: paying your grocery bill from the rental account, or vice versa. That's called commingling, and to a court it's evidence the LLC was never really separate from you. Separate EIN, separate account, separate bookkeeping is what makes the entity a real, respected wall instead of a costume.
Route the profits up to the holding company
After each property LLC covers its own bills, its net rent flows up to the holding company — never to our personal checking. The property LLCs are subsidiaries; distributions move up the chain to the parent.
Beyond keeping the liability separation clean, this simplifies life at tax time. Structured correctly, the profits and losses of the property LLCs roll up so the ownership group is reported through one filing at the holding-company level instead of you chasing a stack of separate returns. Exactly how that flows depends on how the entities are elected and taxed, so this is a conversation to have with your CPA — but the goal is one tidy top-of-the-house picture. (If you want the deduction side handled right, our guide to Schedule E deductions for rental property pairs well with this.)
The title has to actually be in the LLC
This sounds obvious and it's the step people skip: the deed must be recorded in the LLC's name, not yours. An LLC on paper does nothing if the property it's supposed to protect is still legally owned by you personally. You (with your attorney) execute and record a deed transferring title from your name into the property's LLC.
Two cautions here, which is why you do this with a professional: transferring a mortgaged property can implicate the loan's due-on-sale clause, and some jurisdictions charge transfer taxes on the deed. Both are manageable, but you want to know before you record, not after.
How this protects you when a tenant sues
Here's the payoff. Say a tenant at one property is injured and sues over it. Because that property is owned by its own LLC — with its own title, its own bank account, its own insurance — the lawsuit and any judgment are contained to that single LLC. The plaintiff can reach that property's equity and that entity's assets. They generally cannot reach your home, your personal accounts, or your other rentals, because those live in separate entities or in your name behind the holding company's charging-order shield.
One bad incident becomes a problem for one property, not a threat to everything you own. That containment is the entire point of the structure.
Equity stripping: make the target less appealing
Most of these suits are taken on contingency — the attorney only gets paid if they collect. So before they invest, they do collectability math: how much equity and reachable assets are actually here? If the honest answer is "not much," a marginal case gets a lot less attractive.
That's the logic behind equity stripping: placing legitimate debt against a property — a mortgage or a line of credit — so its visible net equity is small. A lawyer who pulls the title and sees a property mostly encumbered by a senior lender's lien sees far less to fight over, and may pass. This has to be real debt for a real purpose — a genuine LOC you can actually use, not a paper sham — or a court can set it aside as a fraudulent transfer. Used properly and set up in advance, it's a quiet, effective deterrent. Used sloppily, it backfires. Get advice.
Insurance is the first wall; the LLC is the second
Structure is not a substitute for coverage — you want both, in layers:
- Each property LLC carries its own insurance: a landlord/dwelling policy covering property loss and liability for that specific property. Insurance is the first line of defense — it pays to defend the claim and to repair or rebuild — long before the entity structure ever matters.
- We also carry a large personal umbrella liability policy on top of everything. If a claim ever blows past a property's coverage, the umbrella adds a substantial personal layer, and only then does the LLC containment become the backstop for whatever remains.
Think of it as depth: insurance absorbs the hit, the umbrella extends the coverage, and the LLC contains whatever is left to a single property. Any one of those alone is thin. Together they're hard to get through.
The operational piece most landlords get wrong
Here's the honest problem with all of this: the structure only works if the money actually flows the way the paperwork says it does. Deed in the LLC, but rent hitting your personal Venmo? You just handed a plaintiff's attorney the commingling argument that collapses the whole thing.
That's the part I built Pacific Rentals Pro to make effortless. You do the one-time bank setup once per property — connect each property LLC's own checking account — and then every tenant's rent is collected online and routed straight to that property's LLC account, automatically. No rent landing in your personal account "just this once." No manual transfers to remember. No Venmo. The books stay clean because the money never had a chance to get dirty — which is exactly the discipline that keeps your corporate veil intact when it matters.
The lawyers, the entities, and the insurance build the walls. Getting each tenant's rent into the right LLC's account, every month, without thinking about it, is what keeps those walls standing.
This article is general information from my own experience as a landlord — it is not legal, tax, or financial advice. Entity structures, charging-order protections, transfer taxes, due-on-sale clauses, and the tax treatment of a holding company all vary by state and by your specific situation. Build your structure with a qualified real estate attorney and CPA licensed in your state before transferring title or moving money.